Global Generative AI In Media And Entertainment Market To Expand At 26.3% CAGR During The Forecast Period
The Business Research Company’s Media And Entertainment Global Market Report 2026 – Market Size, Trends, And Forecast
Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.

The Business Research Company’s Media And Entertainment Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON , UNITED KINGDOM, October 27, 2026 /EINPresswire.com/ — The media and entertainment industry is undergoing a dramatic transformation thanks to generative AI technologies. As demand for more dynamic, personalized, and efficient content creation rises, this sector is witnessing remarkable growth driven by innovations in cloud computing, AI adoption, and automation. Let’s explore the current landscape, major growth factors, key players, and promising segments shaping this evolving market.
Strong Expansion Forecast in Generative AI in Media and Entertainment Market
The generative AI market within media and entertainment is predicted to surpass $8 billion by 2030. It forms about 6% of the broader Generative AI market, which itself is expected to reach nearly $129 billion in the same year. Within the massive Information Technology sector, forecasted at $13.8 trillion by 2030, generative AI in media and entertainment will make up almost 0.1% of the total. This market is anticipated to grow at a compound annual growth rate (CAGR) of 26% through 2030, reflecting strong and sustained momentum.
Request A Free Sample Of The Generative AI In Media And Entertainment Market Report
https://thebusinessresearchcompany.com/sample_request?id=15187&type=smp&name=Generative%20AI%20In%20Media%20And%20Entertainment%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Cloud Computing as a Primary Growth Driver in Generative AI Media Market
One of the main drivers boosting growth is the rising demand for cloud computing. Media companies increasingly rely on cloud-based AI platforms that enable scalable production, faster rendering, and seamless collaboration. These platforms provide studios, developers, and creators with access to powerful AI models without the need for expensive hardware investments. This shift streamlines workflows in video production, animation, gaming, and digital content development, contributing roughly 2.0% annual growth to the market.
Expanding Adoption of AI Tools in Content Creation
Another significant growth factor is the growing use of AI in various creative processes. AI-powered tools are transforming scriptwriting, video editing, visual effects, music composition, and digital asset generation. These technologies reduce production times, enhance personalization, and improve content quality across formats. Investments by entertainment companies and tech firms are accelerating this integration, adding about 1.5% annual growth to the market.
Access The Detailed Generative AI In Media And Entertainment Market Report Here
https://thebusinessresearchcompany.com/report/generative-ai-in-media-and-entertainment-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Wider Use of AI Enhancing Audience Experiences
The increasing deployment of artificial intelligence in audience engagement is also pushing the market forward. AI enables automated dubbing, virtual characters, smart recommendations, and interactive storytelling, all of which deepen viewer involvement. Media organizations harness generative AI to automate repetitive tasks and develop immersive entertainment experiences, driving another 1.0% annual growth contribution to the industry.
How AI-Powered Media Copilot Tools Are Advancing the Market
Media copilot technology powered by AI is revolutionizing generative AI applications by improving content performance analysis, boosting workflow automation, and supporting smarter decision-making. For instance, in April 2024, Symphony Innovation LLC introduced an AI-driven Media Copilot platform that merges predictive and generative AI to evaluate content distribution and revenue models. This tool enhances operational efficiency, optimizes media strategies, and enables advanced AI-supported creative and business workflows.
Text-to-Image Generation Dominates Generative AI Market Segments
Among the various types of generative AI applications in media and entertainment, text-to-image generation is projected to hold the largest market share by 2030, accounting for 31% or $3 billion of the total. This segment benefits from AI platforms that accelerate visual content creation, meet advertising and digital media needs, support entertainment graphics, and steadily improve in accuracy, customization, and output quality.
Breakdown of Generative AI Market by Offerings, Deployment, and Applications
The generative AI market is segmented by offerings into solutions and services. Deployment modes include cloud-based and on-premise platforms. Applications cover a broad range such as gaming, film and television, advertising and marketing, music and sound production, virtual reality (VR), augmented reality (AR), and other media-related uses.
Asia-Pacific Emerges as the Leading Region in the Generative AI Media Market
By 2030, Asia-Pacific is expected to lead the generative AI in media and entertainment market with a valuation of $2.8 billion, up from $0.7 billion in 2025 and growing at a CAGR of 31%. This rapid growth is fueled by the expanding digital entertainment sectors in China, India, Japan, and South Korea. Key factors include widespread use of AI content creation tools, investment in AI infrastructure, demand for personalized media, robust gaming and streaming markets, and deeper integration of AI in creative production.
The USA Holds a Significant Share in Generative AI Market Growth
The United States is projected to be the top single country market in this sector by 2030, reaching $2.3 billion from $0.8 billion in 2025, driven by a 23% CAGR. Growth is supported by leading AI companies and entertainment studios, high adoption of AI video and image generation tools, extensive use of generative technologies in film and digital marketing, and ongoing advances in AI models that enhance content quality and production efficiency.
Segments Contributing Most to Market Growth and Value
Text-to-image generation, image-to-image generation, music generation, video generation, and 3D modeling and animation are the key segments expected to add over $5.4 billion in value by 2030. Specifically, text-to-image generation will grow by $2 billion, with image-to-image and music generation each contributing $1 billion, video generation another $1 billion, 3D modeling and animation about $0.3 billion, and other types roughly $0.1 billion. This growth is driven by demand for automated and personalized creative assets, advances in generative models, and the push for more immersive digital experiences.
Market Fragmentation and Leading Players in Generative AI Media and Entertainment
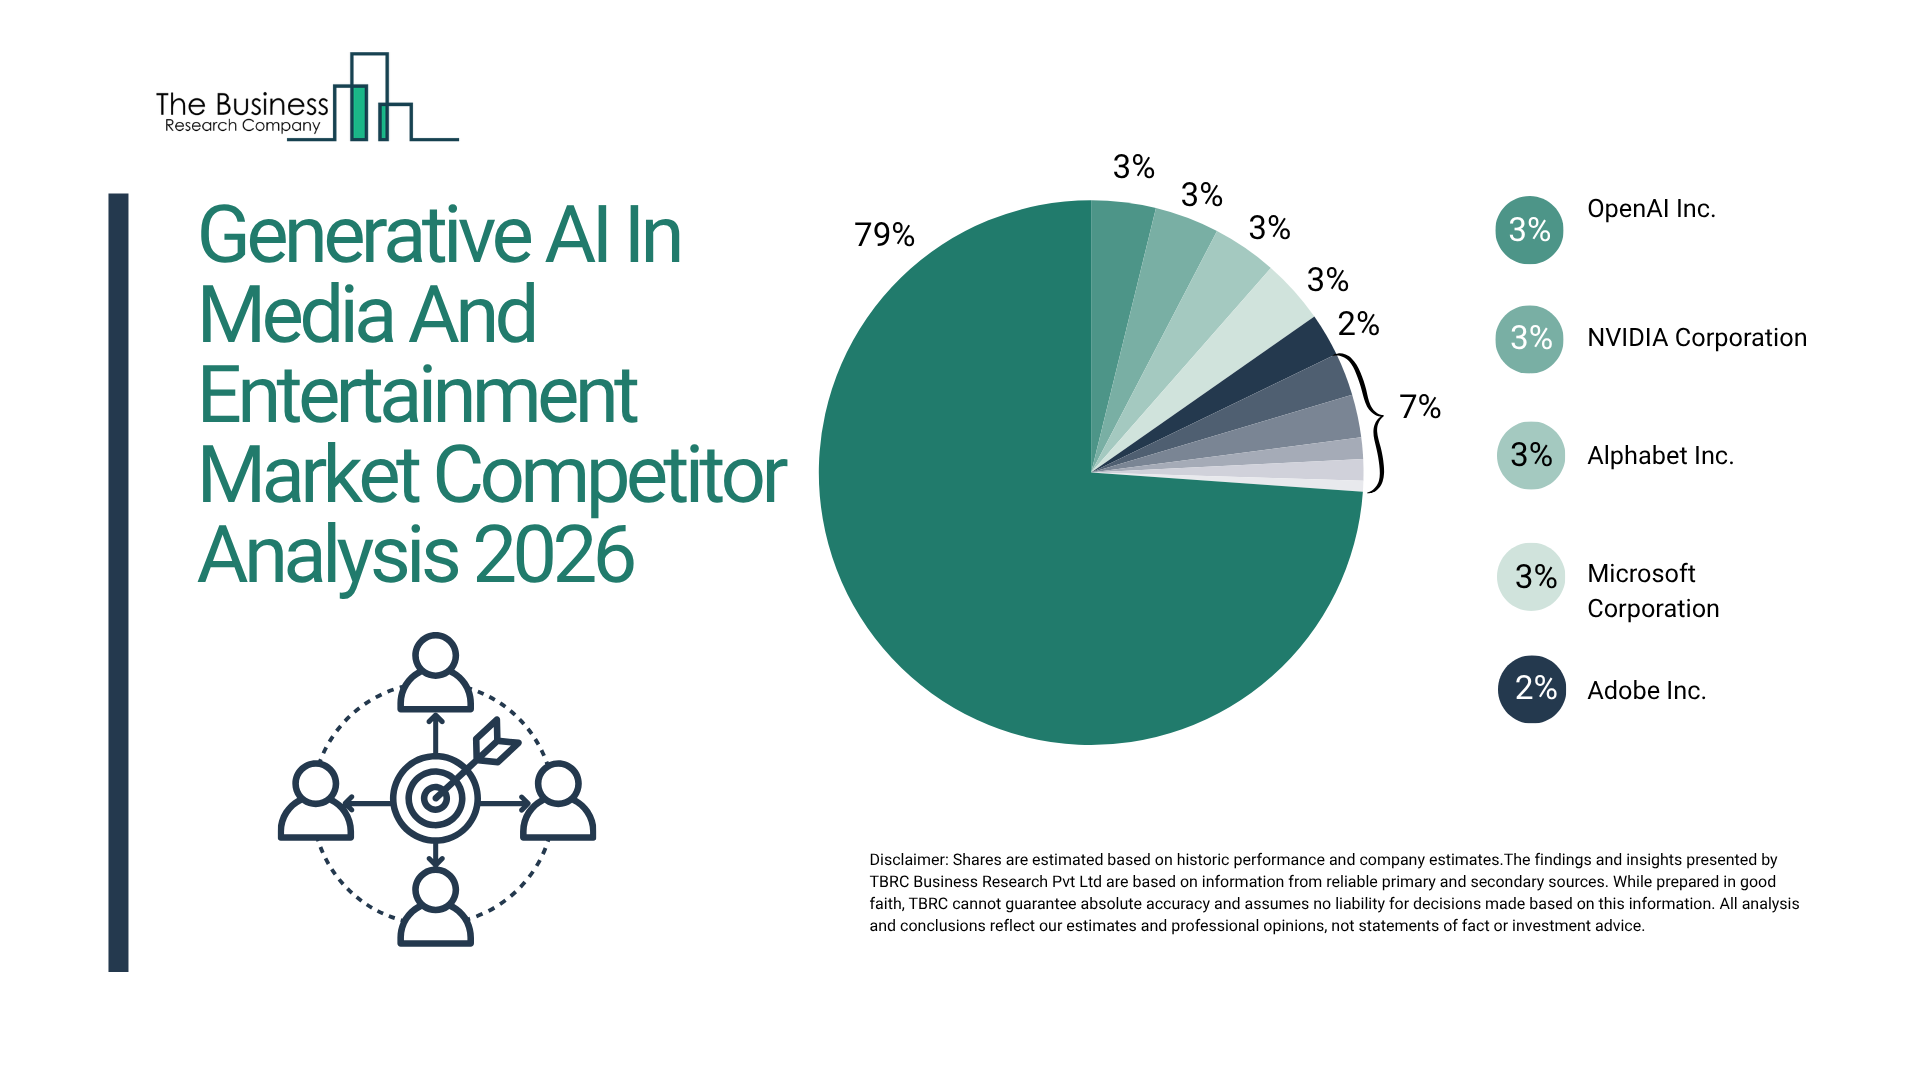
The market is moderately fragmented, with the top ten companies accounting for 21% of total revenue in 2025. High barriers to entry include the need for advanced AI development, extensive computing infrastructure, ongoing algorithm enhancements, and scalable content generation capabilities. Leading firms maintain their positions through diversified AI platforms, strong media partnerships, comprehensive cloud ecosystems, and continuous innovation in multimodal models and synthetic content. As demand grows for AI-generated video, personalized entertainment, and automated production, these companies are poised to expand through technological advances and strategic collaborations.
Key Market Share Holders Among Leading Companies
In 2025, the top companies and their market shares include: OpenAI Inc., NVIDIA Corporation, Alphabet Inc., and Microsoft Corporation each with 3%, Adobe Inc., Meta Platforms Inc., and Amazon Inc. each holding 2%, DeepMind Technologies Limited and Tencent Holdings Ltd. at 1%, and Stability AI with 0.5% market share.
Strategies Adopted by Market Leaders
Major players are competing by utilizing AI-powered virtual production to boost creative content, deploying multimodal generative models to reshape digital media experiences, applying synthetic content to speed up production workflows, forming strategic alliances to enhance AI innovation, and offering cloud-based platforms that support scalable content generation.
OpenAI Inc.’s Leadership in Language and Image Models
OpenAI Inc. leads the global market in sales for generative AI within media and entertainment, holding a 3% share in 2025. Its AI division develops large language models, image generation systems, AI assistants, and creative content solutions that enhance digital storytelling, automate media production, enable personalized experiences, and strengthen creative workflows across entertainment and communication platforms.
Overview of Major Companies in the Generative AI Media Ecosystem
The competitive landscape includes companies such as OpenAI Inc., NVIDIA Corporation, Alphabet Inc., Microsoft Corporation, Adobe Inc., Meta Platforms Inc., Amazon Inc., DeepMind Technologies Limited, Tencent Holdings Ltd., Stability AI, Autodesk Inc., Unity Software Inc., Epic Games Inc., IBM, Samsung, Netflix Inc., Baidu Inc., Cohere Inc., Runway AI Inc., Figma, Snap Inc., Leonardo.Ai, Vimeo, D-ID, Synthesis AI, Vyro.ai, and Fox Sports AI Media Operations.
Supply Chain and Key Users Supporting the Market
Raw material and hardware suppliers include companies like NVIDIA Corporation, Advanced Micro Devices Inc., Taiwan Semiconductor Manufacturing Company Limited, Samsung Electronics, SK Hynix Inc., Micron Technology Inc., Intel Corporation, Broadcom Inc., Marvell Technology Inc., Qualcomm Incorporated, Arm Holdings plc, Super Micro Computer Inc., Dell Technologies Inc., Hewlett Packard Enterprise, Cisco Systems Inc., Arista Networks Inc., Applied Materials Inc., ASML Holding N.V., Lam Research Corporation, and KLA Corporation.
Wholesalers and distributors facilitating market reach include Amazon Web Services Inc., Microsoft Azure, Google Cloud Platform, Oracle Corporation, IBM Corporation, Salesforce Inc., Accenture plc, Capgemini SE, Cognizant Technology Solutions, Infosys Limited, Tata Consultancy Services, Wipro Limited, Tech Mahindra, HCL Technologies, Adobe Inc., Autodesk Inc., Unity Software Inc., Epic Games Inc., Runway AI Inc., and Stability AI.
End users span top media and entertainment companies such as Netflix Inc., The Walt Disney Company, Warner Bros. Discovery Inc., Paramount Global, Sony Pictures Entertainment, Universal Pictures, Fox Corporation, Comcast Corporation, Spotify Technology, Electronic Arts Inc., Take-Two Interactive Software Inc., Ubisoft Entertainment, ByteDance Ltd., Tencent Music Entertainment Group, Snap Inc., Vimeo Inc., Canva Pty Ltd., Getty Images Holdings Inc., Shutterstock Inc., and WPP plc.
Expanded capabilities in our 2026 market reports:
• Market attractiveness scoring and analysis
• Total addressable market (TAM) analysis
• Company scoring matrix graphics and tables
• Excel-based forecasting dashboards
• Market hotspots infographics
• Key technologies and future trend analysis
• Updated graphics and tables
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company.
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery